Credit cards offer convenience and security, but behind the attractive offers and easy spending, lies a costly financial reality. Are Irish consumers sufficiently protected?
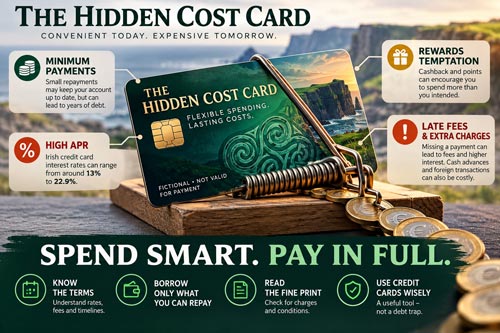
Credit cards are useful for online shopping, emergencies and managing short-term expenses. However, high interest rates, minimum repayments and additional charges can quietly turn everyday purchases into long-term debt.
In Ireland, credit card providers operate under consumer protection rules, but understanding the risks remains essential.
The Minimum Repayment Trap.
According to Ireland’s Competition and Consumer Protection Commission (CCPC), minimum monthly repayments are generally around 2% – 5% of the outstanding balance.
Paying only this amount may keep your account up to date, but interest continues accumulating.The CCPC illustrates that a €1,000 balance at 17% interest, with monthly repayments of €50, takes approximately two years to clear. Increasing repayments to €100 reduces this to around 11 months.
Consumer Tip: Pay your balance in full whenever possible, or substantially more than the minimum.
High Interest and Hidden Charges.
The CCPC reports that Irish credit card interest rates can range from approximately 13% to 22.9%.
Additional charges may include late payment fees, foreign currency transaction fees and cash withdrawal charges.
Ireland also imposes an annual €30 government stamp duty on credit card accounts, collected by card providers on behalf of Revenue.
Consumer Tip: Compare Annual Percentage Rates (APRs), examine fees and avoid withdrawing cash using credit cards.
Rewards That Encourage Overspending.
Cashback, loyalty points and promotional offers can encourage spending beyond genuine needs.
A reward worth €10 is hardly beneficial if obtaining it requires an unnecessary €500 purchase!
Consumer Tip: Never buy something simply to qualify for rewards. A higher credit limit is not additional income.
The Interest-Free Period Misunderstanding.
Many Irish credit cards offer an interest-free period of up to approximately 56 days. However, this generally depends on paying the full amount owed by the deadline. Paying only part of the balance may trigger interest on purchases from their transaction dates.
Consumer Tip: Read promotional terms carefully and arrange automatic repayments.
What Protection Do Irish Consumers Have?
Ireland’s strengthened Central Bank Consumer Protection Code 2025, effective from 24th March 2026, places statutory obligations on regulated financial providers to safeguard customers’ interests.
These include requirements concerning fair treatment, effective consumer information, responsible product design and support for vulnerable customers. Consumers also have important avenues for redress:
CCPC: Independent information, comparison tools and consumer guidance.
Financial Services and Pensions Ombudsman (FSPO): Free, independent complaints resolution after raising the issue with the provider.
MABS: Free, confidential budgeting and debt advice.
Chargeback: Consumers may be able to dispute eligible card transactions through their provider.
The Way Forward: Protection Through Awareness
Irish regulators have strengthened consumer safeguards, but regulation alone cannot prevent every financial mistake or unsuitable borrowing decision.
Greater financial education, transparent pricing, responsible lending and proactive monitoring of harmful financial practices remain important.
Credit cards should provide financial flexibility, not financial dependency.
The safest approach is simple: borrow only what you can repay, monitor your spending and understand every charge.
Should Irish banks be required to do more to prevent consumers becoming trapped in long-term credit card debt?




Leave a Reply